Dubai · 9 min read
Dubai Off-Plan Payment Plans, Explained Without the Brochure
60/40, 1% a month, post-handover: Dubai's off-plan payment plans look alike and behave very differently. How to read one before you sign it.
05-Sep-2026
A Dubai payment plan fits on a single line of a brochure. 20/80. 60/40. 1% a month. Three years after handover. It is the most persuasive line on the page, and the one people read least carefully, because a percentage feels like a fact and a fact feels like it needs no reading.
It does. Two plans with the same headline can cost you very different amounts, at very different times, with very different consequences if something goes wrong. This note is about the second reading.
If you have not yet read the rules on both sides for an Indian buyer, start there. Everything below assumes the money can leave India cleanly. This is about what happens when it lands.
Why are Dubai plans so generous?
Because developers sell off-plan to fund construction, and in a competitive market the payment plan is one of the main things they compete on. A buyer who would never find the full price in one go can often manage a booking amount and a predictable monthly or quarterly instalment. A developer who offers that buyer a gentle plan sells more units, earlier.
None of that is sinister. It is worth remembering that the plan is a product, designed by the seller, and priced accordingly.
The four shapes
Almost every plan you will see is a variation on one of four shapes.
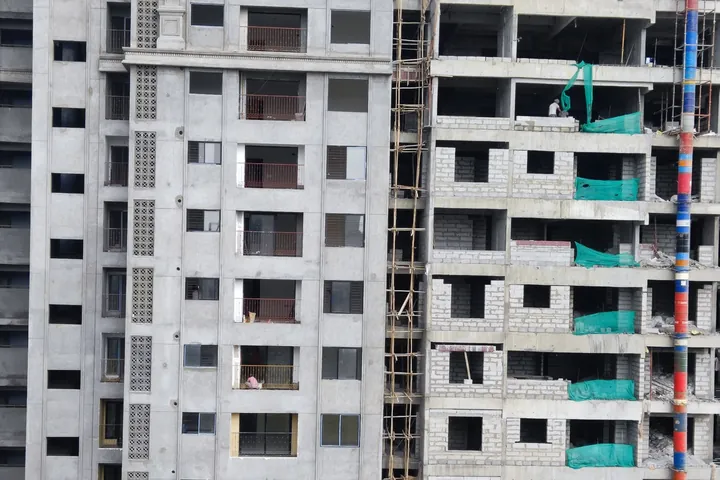
The construction-linked plan. You pay a booking amount, often somewhere between 10 and 20 per cent, and then pay further instalments as the building reaches defined milestones: foundations, structure, facade, and so on. The balance falls due at handover. Your payments track the building's progress, which is the reassuring part. The less reassuring part is that you do not control the timing; a fast build means fast bills.
The time-based plan. Instalments fall due on fixed dates, whatever the building is doing. A common variant is the monthly plan, where you pay a small, fixed percentage every month through construction – the 1 per cent a month structure that Danube Properties popularized is the best-known example. These are easy to budget for and easy to remit against an annual limit.
The handover-weighted plan. Labelled 50/50, 60/40 or similar, it means you pay the first number during construction and the second at handover. A large lump at handover is often the moment buyers plan to use a mortgage, or the sale of something else.
The post-handover plan. You pay part of the price during construction, receive the keys, and keep paying for one to several years after handover. This is the plan that makes buyers most sanguine, and with reason: you can let the flat and use the rent towards the remaining instalments. It is also the plan whose fine print deserves the most attention, because you are living in, or letting, something you have not yet finished paying for.
What the percentages are a percentage of
The plan's percentages are almost always percentages of the purchase price. They are not the whole bill.
On top of the price, budget for the Dubai Land Department's 4 per cent transfer fee, usually payable at booking when the unit is recorded on Oqood, the interim register; the registration and administration fees that go with it; and, from handover, the annual service charge, set per square foot.
So a 10 per cent booking amount is closer to 14 per cent of the price in cash on day one, plus fees. Developers sometimes offer to waive part or all of the transfer fee as a promotion. The fee is still paid; someone has decided who pays it, and it is worth asking what else in the deal moved to make room.
The headline price and the real price
Here is the comparison almost nobody makes. A gentle plan is not free. A developer that offers you five years to pay is financing you for five years, and the cost of that finance is built into the price.
Ask what the same unit costs on a shorter plan, or for a larger payment upfront. Sometimes the answer is the same. Often it is not. The difference between the two is the effective interest you are paying for the comfortable plan, and once you see it as a number you can compare it with the alternatives: a mortgage at handover, or money you already have.
Take a hypothetical buyer, Faisal, choosing a one-bedroom in Arjan. Option one is a construction-linked plan finishing at handover. Option two is a post-handover plan stretching three years past the keys, at a higher price. Option two feels easier. Whether it is cheaper depends entirely on the gap between the two prices, the rent he can realistically collect from handover, and the service charge he will pay from the same date. Put those numbers side by side and the right answer is usually obvious. Leave them in the brochure and it never is.
Escrow, again, because it matters
Every off-plan payment in Dubai should go to the project's escrow account, held with an approved bank and registered for that specific project. The developer draws from it as construction progresses, under the supervision of the regulator. That is the single most important protection you have, and the plan only protects you if every instalment goes where it should.
You can check a project's registration and its reported construction progress through the Dubai Land Department's official channels, including the Dubai REST app. If a milestone invoice arrives and the reported progress does not match, ask before you pay.
The currency underneath the plan
The dirham is pegged to the US dollar. The rupee is not. For an Indian buyer paying over three or five years, that means the rupee cost of each instalment moves with the exchange rate, even though the dirham amount never changes.
Over a long plan, that drift can be meaningful in either direction. It is not a reason to avoid a long plan. It is a reason not to budget for the whole thing at today's exchange rate, and to keep some headroom.
It also matters for timing under the Liberalised Remittance Scheme. A plan whose instalments in any financial year would exceed what the people on the title can remit between them is a plan that needs rearranging before you sign, not after.
The yield you are shown, and the one you get
Off-plan sales presentations often include a rental yield: the expected annual rent as a share of the price. It is a useful number, provided you know what has been left out of it.
The service charge, from handover, every year.
The property manager's fee, if you are not in Dubai to manage the tenancy yourself.
A month or two of vacancy between tenants, and the cost of repainting and repairs when one leaves.
The cost of furnishing, if the yield assumes a furnished let.
Take those out and you have a net yield, which is the only one worth comparing with a fixed deposit at home. It is usually lower than the headline. That does not make the purchase a bad one. It makes the comparison an honest one.
What happens if you stop paying
Nobody plans to default. Plans change anyway: a job moves, a market turns, a family need arrives. The same questions about waiting, risk and certainty that Chennai buyers weigh in under construction or ready to move apply here, with a currency on top.
Dubai's law on the interim register sets out what a developer may do if a buyer of an off-plan unit stops paying. The developer has to notify the buyer through the Land Department and give a period to remedy the default. If the buyer does not, what the developer may keep from the amounts already paid depends on how far construction has progressed, and the share it may retain rises as the project nears completion.
The lesson is simple. A plan that stretches you to the limit in the early years carries more risk than its headline suggests, because the cost of walking away grows as the building rises. Choose a plan you could keep paying through a bad year.
Selling before handover
Many buyers enter off-plan intending to sell before completion. It can work. But most developers will only allow a unit to be assigned to a new buyer once a minimum share of the price has been paid, they usually charge a fee for issuing the permission, and the new buyer pays the Land Department's transfer fee again on the resale. Check all three before you treat an early exit as your plan rather than your option.
At handover
On a construction-linked or handover-weighted plan, handover is when the large final payment falls due, and when the title deed is issued once the price is paid. Inspect the unit thoroughly before you accept it and record every defect in writing. Connect the utilities, register any lease on Ejari, and set up the service charge.
On a post-handover plan, read the clauses on when the title deed is issued and on what terms, what happens to the unit if a post-handover instalment is missed, and whether you may lease it before you have paid in full. The answers vary by developer and by project.
The developer behind the plan
A payment plan is only as good as the developer who has to deliver the building at the end of it. Before you compare plans, compare developers.
How many projects has this developer handed over in Dubai, and how close to the original date? The Land Department's records and a few conversations with owners in a finished building will tell you more than any sales presentation.
What does a finished building of theirs look like three years on? Visit one. Look at the lobby, the lifts and the service charge.
How many projects do they have under construction now, and how far along are they? A developer stretched across too many launches is a developer whose next delay may be yours.
A generous plan from a developer with a patchy record is not generous. It is a longer wait for the same uncertainty.
Mortgages at handover
Many buyers plan to pay the handover balance with a mortgage from a UAE bank. Banks in Dubai do lend to non-residents on completed property, usually for a lower share of the value than they would lend to a resident, and with their own valuation deciding the amount. For a resident Indian, the foreign exchange position on borrowing abroad needs a professional answer before you rely on it. In either case, apply early: a mortgage that is not approved by the handover date leaves you with a large bill and very few options.
Where off-plan is busiest
Most off-plan activity aimed at Indian buyers sits in the newer communities. Jumeirah Village Circle and Jumeirah Village Triangle for compact, rentable apartments. Arjan, Al Furjan and the wider Dubailand area for newer, roomier stock. Meydan and Business Bay at the more central end. You can compare one-bedroom and two-bedroom apartments across the city, or start with everything in Dubai.
A reading list for any plan
What is the price on this plan, and on the shortest plan the developer offers?
What is due on day one, including the transfer fee and every administrative charge?
When does each instalment fall due, and what triggers it: a date, or a milestone?
What is due at handover, and how will I fund it?
What does the service charge come to each year, and from when?
Can I assign the unit before handover, after how much, and for what fee?
What does the agreement say about a missed instalment?
What can my family remit each financial year, and does the plan fit inside it?
Every one of those has an answer in the sale and purchase agreement. If it does not, that is an answer too.
The plan is the product
A payment plan is the developer's financing, the buyer's budget and a schedule of obligations, all at once – generous yet binding, simple yet easy to misread. Read it as all three and it can make a Dubai purchase genuinely comfortable. Read it as a percentage and it will read you instead.
If you are weighing two plans, or two projects with two very different plans, send them to us. We will lay them side by side, in rupees as well as dirhams, and tell you which one we would sign.