Dubai · 9 min read
Buying Property in Dubai from India: The Rules on Both Sides
A Dubai flat is two transactions, one under Indian rules and one under Dubai's. What LRS, TCS, the DLD and escrow mean for a buyer in Chennai.
14-Aug-2026
Dubai is about four hours from Chennai by air. On paper, it is much further. A flat in Jumeirah Village Circle bought by a family in Anna Nagar is really two transactions stitched together: one that has to satisfy the Reserve Bank of India and the Indian tax department, and one that has to satisfy the Dubai Land Department. Get either half wrong and the other half does not much matter.
The good news is that both halves are well-trodden. Thousands of Indian residents have bought in Dubai under exactly these rules. The trick is to do it in the right order, with the right paper, and without believing everything you hear in a hotel ballroom on a Saturday afternoon.
This note is for Indian residents. If you are an NRI already living in the UAE, the Indian side is lighter and the Dubai side is the same; talk to us and we will walk you through the difference.
Can an Indian resident actually buy in Dubai?
Yes. Indian residents can buy property abroad under the Liberalised Remittance Scheme, which lets each resident individual send up to USD 250,000 out of India in a financial year for permitted purposes. Buying immovable property overseas is one of them.
That limit is per person, not per family. A couple can each use their own limit, and family members can combine their remittances towards a property they will own jointly, subject to the conditions in the scheme. Your bank will ask for a declaration of purpose and, usually, a copy of the booking form or sale agreement.
What the scheme does not do is turn every source of money into an acceptable one. The funds have to be your own, sent through a bank, to the right account in Dubai. If you are thinking about a mortgage from a UAE bank while living in India, stop and get advice first: borrowing abroad as a resident raises foreign exchange questions that need a professional answer before you sign, not after.
TCS: the tax that is collected before it is owed
When you send money abroad under the scheme for purposes like property, your bank collects tax at source. At the time of writing, remittances above ₹10 lakh in a financial year attract TCS at 20 per cent on the amount over that threshold.
That number gets people's attention, and it should. But TCS is not an additional tax. It is collected in advance and credited against your income tax for the year, so you claim it when you file your return, and get a refund if it exceeds what you owe. The real cost is the cash it ties up for a few months. Plan your remittances with that in mind, and with your chartered accountant in the room.
Your Indian tax return
A resident Indian is taxed on worldwide income, and that includes rent from a flat in Dubai. The UAE does not levy personal income tax on that rent, and the double taxation agreement between the two countries governs how the income is treated. Your CA will know how to report it.
More importantly, a resident who owns assets abroad must disclose them in the foreign assets schedule of the Indian income tax return, every year, whether or not they earned anything that year. The penalties for leaving it out are severe enough to wipe out several years of rental yield. It is the step most easily forgotten once the excitement of the purchase is over, and the easiest to avoid.
Now the Dubai side: where foreigners can buy
Dubai allows foreign nationals to buy freehold property in designated areas, and those areas include almost every community an Indian buyer is likely to consider. Dubai Marina, Jumeirah Lake Towers, Business Bay, Jumeirah Village Circle, Arjan, Al Furjan, Dubai Sports City and Dubai Silicon Oasis are all freehold for foreign buyers.
Freehold means what it says: you own the unit outright, with a title deed issued by the Dubai Land Department in your name.
Two regulators called RERA
Here is a pun the two governments did not intend. India has RERA, the regulator created by the 2016 Act. Dubai has RERA too: the Real Estate Regulatory Agency, the regulatory arm of the Dubai Land Department. Same letters, different laws, different jobs. A buyer who has read what TNRERA checks will find the Dubai version familiar in spirit, but should not assume the details carry over.
Dubai's RERA registers developers and projects, licenses brokers, approves advertisements through a permit system called Trakheesi, and oversees the escrow rules that protect off-plan buyers. You can check a project, a developer and a broker yourself through the Dubai Land Department's official channels, including its Dubai REST app. Do.
Escrow: where your money is supposed to go
For off-plan property, Dubai law requires a developer to sell through an escrow account registered for that specific project, held with an approved bank. Buyers' payments go into that account, and the developer draws on it as construction progresses.
The practical rule is simple. Every payment for an off-plan unit should go to the project's escrow account, in the developer's name, with the project named in the reference. Not to a broker. Not to a "holding" account. Not to anybody's personal account, however friendly. If anybody asks you to pay somewhere else, the conversation is over.
The fees you will actually pay
The Dubai Land Department charges a transfer fee of 4 per cent of the property value on registration, along with smaller administrative and registration trustee fees. On off-plan purchases, the 4 per cent is normally due at or near booking, when the sale is recorded on the interim register, which is known as Oqood. Developers sometimes run offers that cover part or all of it; read those offers carefully, because the fee does not disappear, it moves.
There is no stamp duty in the Indian sense, no GST on a residential purchase, and no annual property tax. There is, however, an annual service charge, which pays for the building's maintenance, security and common areas, and is charged per square foot at rates approved by the regulator. Ask for the current figure before you buy, and factor it into any rental yield you are being shown. A yield quoted before service charges is a brochure yield.
Checking the broker
Dubai licenses its brokers individually. A broker registered with the regulator carries a broker registration number, and the brokerage they work for has an office registration number of its own. Ask to see both, and check them through the Land Department's official channels before you share a passport copy or pay a reservation fee.
A registered broker is also the person whose name should appear on the paperwork alongside yours. If the person you have been talking to on WhatsApp for three weeks turns out not to be on any document, ask who is, and why.
Off-plan or ready?
Most Indian buyers enter Dubai through off-plan property, because the payment plans are friendly to a buyer who is remitting money over time under an annual limit. A plan that spreads payments across construction, and sometimes past handover, lines up neatly with a USD 250,000 annual ceiling.
Payment plans are a subject in their own right, and the details matter more than the headline percentages, so we have given them their own note on Dubai off-plan payment plans.
Ready property suits a buyer who wants rent from day one, but it usually needs the full price in a shorter window, which makes the remittance limit the binding constraint. Families sometimes solve this by buying jointly and remitting from more than one person's limit.
The Golden Visa, briefly
A property investment of at least AED 2 million can qualify the owner for Dubai's ten-year Golden Visa, subject to the conditions in force when you apply. It is a genuine benefit for some families. It should not be the lodestar of the decision. Buy a property you would want at AED 1.9 million, and treat the visa as a bonus if the right one happens to cross the line.
Where Indian buyers tend to look
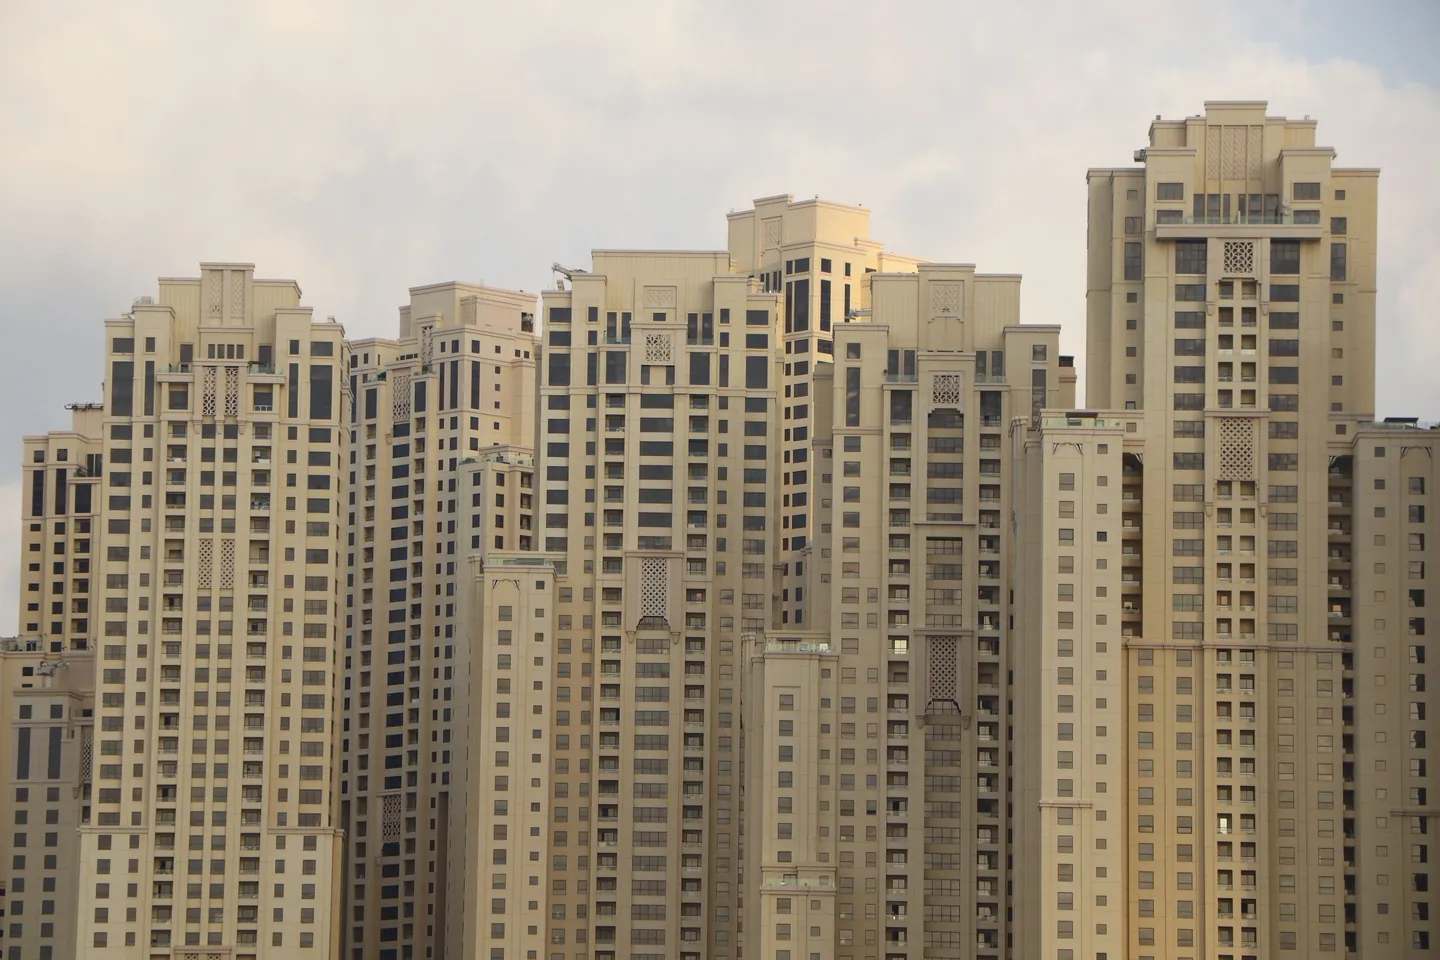
Dubai's market is a set of quite different neighbourhoods wearing one skyline.
Jumeirah Village Circle is the mid-market workhorse: dense, central to the new Dubai, popular with tenants, and full of studios and one-bedroom apartments at accessible prices.
Business Bay sits beside Downtown along the Dubai Water Canal, mixes offices and residences, and appeals to buyers who want a city address.
Arjan and Dubai Sports City, in the wider Dubailand area, offer newer stock, more space for the money, and a quieter pace.
Al Furjan has the metro on its doorstep and a more residential, family feel.
Dubai Silicon Oasis and International City sit on the route of the Dubai Metro's planned Blue Line, and sit at the more affordable end of the market.
We are channel partners to Danube Properties, whose projects run across several of these communities, and we work with other developers in the city as well. You can browse what is open across all of Dubai.
A buyer's sequence, start to finish
Take a hypothetical family: Ravi and Shalini in Chennai, buying a one-bedroom off-plan in JVC as a rental, held jointly.
They shortlist with an agent who is registered in Dubai or works with one who is, and check each project on the Land Department's channels.
They speak to their CA about TCS, the remittance plan for each of them across financial years, and how the rent will be reported.
They sign the reservation form and pay the booking amount to the project's escrow account, from their own Indian bank accounts, through the scheme.
They pay the 4 per cent transfer fee and the unit is registered on Oqood in their names.
They pay instalments into escrow as construction progresses, each remittance declared under the scheme.
At handover, they inspect the unit, record snags, pay any balance due, and receive their title deed.
They declare the asset in the foreign assets schedule of their Indian return, every year from then on.
Nothing on that list is exotic. Every step is skippable. Every skipped step is expensive.
Renting it out
Most Indian buyers in Dubai buy to let, and the rental side has its own rules.
A long-term lease is registered through Ejari, the Dubai system for recording tenancy contracts, and the rent is usually paid in a small number of cheques across the year. Many owners living in India appoint a licensed property management company to find tenants, collect rent, handle maintenance and deal with the tenancy registration, for a fee that comes out of the yield.
Short-term holiday letting is a different business. A unit let by the night needs a holiday home permit from Dubai's tourism authority, and the building's own rules may restrict it. The headline nightly rates can be attractive; the management, cleaning, furnishing and vacancy costs are what decide whether it beats a plain annual lease.
Wherever the rent is paid, it remains income that a resident Indian reports in India.
Selling later
When you sell, the buyer's side usually bears the Land Department's transfer fee, though that is a matter of agreement rather than law. The UAE does not tax the gain. India does: a resident is taxed on a gain from a foreign property in the same way as on any other capital asset, with credit for any foreign tax where the treaty allows it. And the proceeds you bring home should come through the banking channel, so that the trail you started under the remittance scheme ends as cleanly as it began.
The short version
Indian rules decide how the money leaves. Dubai's rules decide where it lands. A good purchase satisfies both, in order, with paper for every step.
We do this from Chennai, for families who want an asset abroad without a weekend of guesswork. If Dubai is on your list, tell us about your budget and your plans, and we will bring both sets of rules to the first conversation.